SEBI cleared Cult.fit's IPO on 12 October 2026, and the market is now waiting for a price band. Whether or not you'd buy the shares, the draft prospectus is one of the most useful public documents an Indian founder can read if they're building anything with physical locations. It shows 708 fitness centres run on three different operating models, an adjusted EBITDA that turned positive at ₹144.78 crore, and a loss to owners that is still ₹247.53 crore. Both numbers are true at the same time. Here's how to read them, and what the filing says about the trade-offs of scaling in the real world.
The headline numbers
From the DRHP figures reported by INDmoney (₹ crore):
Revenue: 926.66 in FY24, 1,215.54 in FY25, 1,720.61 in FY26.
Adjusted EBITDA: minus 140.19, minus 33.53, then plus 144.78, an 8.41% margin in FY26.
Loss attributable to owners: 887.2, 479.69, then 247.53.
The trajectory is real: revenue up nearly 86% in two years while losses fell by more than two-thirds. As of 31 March 2026, Cult.fit had about 9.87 lakh paid members across 708 centres in 77 cities.
How it's EBITDA-positive and still loss-making
Adjusted EBITDA leaves out several costs by design. In Cult.fit's case, the big ones sit below that line: INDmoney puts FY26 depreciation and amortisation at about ₹227.11 crore and finance costs at ₹125.45 crore. Together that's more than double the adjusted EBITDA.
That's what a network of hundreds of fitted-out, leased gyms costs to build and finance. The equipment wears out, the interiors get redone, and money borrowed to open centres has to be serviced. None of it shows up in "adjusted EBITDA", and all of it is real cash at some point. If you're pitching a physical business on an EBITDA number, expect investors who've read this filing to ask what sits underneath. It's the same lesson as what "turned profitable" really meant for Ather: always ask which profit.
Three operating models in one company
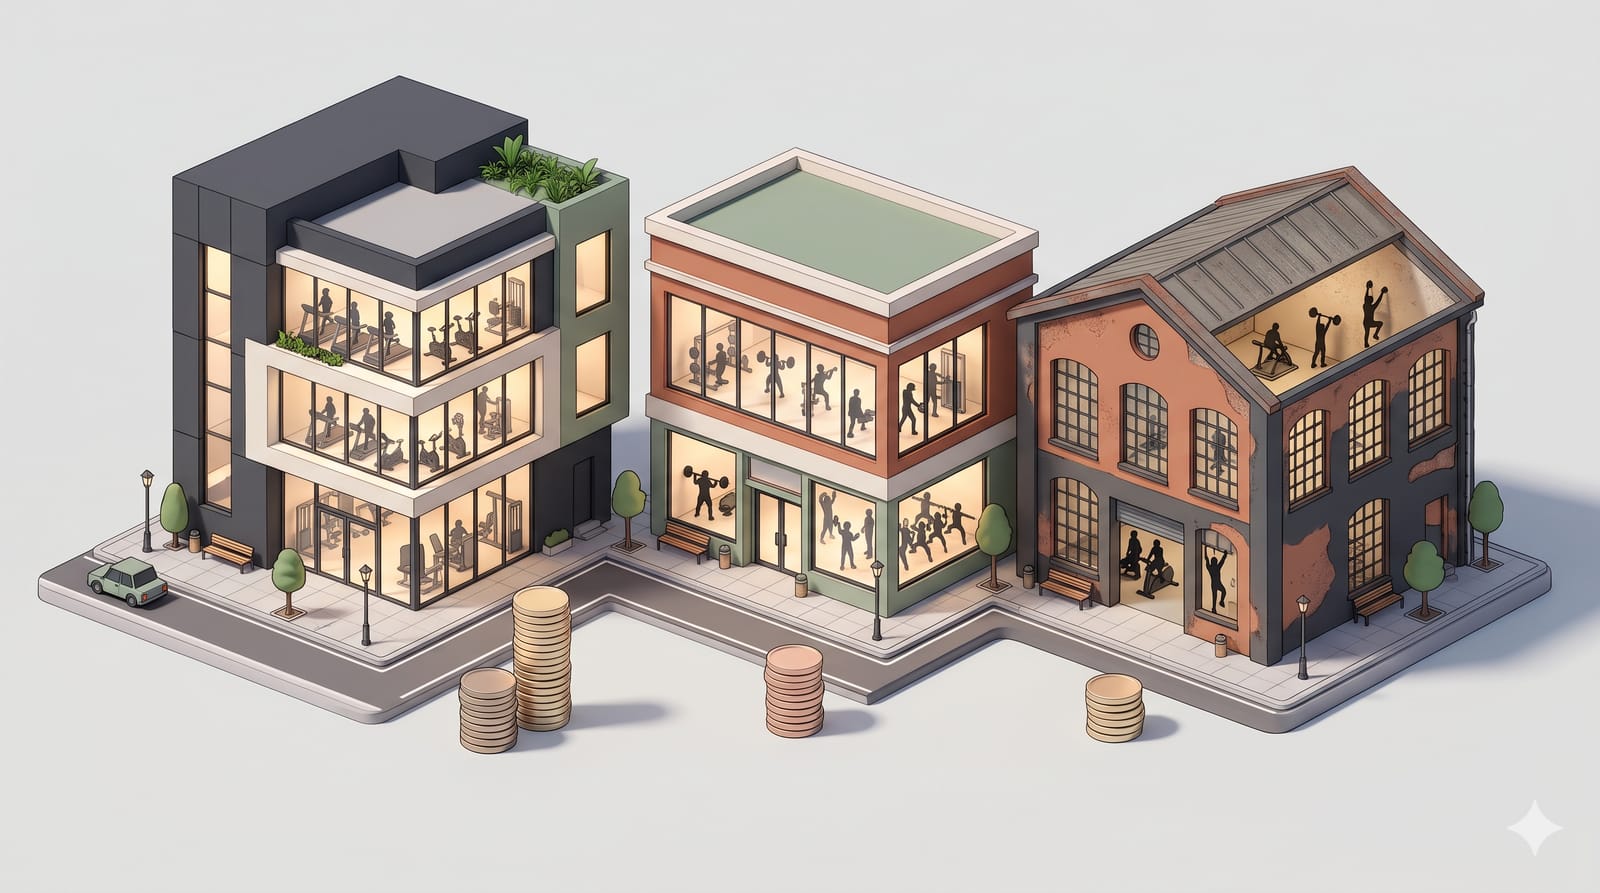
The most interesting detail for founders is the mix. Per Inc42's read of the filing, of the 708 centres, 218 are company-owned, 288 are franchise-run and 202 are run by independent owners. That's three different answers to the same question: who pays to build the gym, and who keeps the margin?
Company-owned
Full control over experience, pricing and brand. Also full exposure to rent, fit-out costs and empty classes on a slow Tuesday. This is where depreciation and finance costs come from.
Franchise
Someone else funds the centre; the brand earns a share. Faster expansion with less capital, at the cost of control. One badly run franchise can dent a brand built by hundreds of good ones.
Independent owners
Closest to a marketplace: existing gyms plug into the network. The least capital and the least control, and the customer may not notice the difference until something goes wrong.
The DRHP coverage doesn't break out profitability by model, so you can't tell from public numbers which one earns the best return. But the mix itself is a signal: Cult.fit is not betting on a single answer. If you're building a clinic chain, a cloud kitchen network or a co-working brand, this is the decision you'll face too, and it's rarely all-or-nothing.
Where the IPO money goes
Of the fresh issue of up to ₹950 crore, the DRHP earmarks, per INDmoney:
₹276.6 crore for new centres
₹217.5 crore for lease, rent and licence payments on existing identified centres
₹120 crore to repay borrowings
₹75 crore for marketing
₹23.4 crore for new Cultsport stores
Read the second line twice. Using IPO money to pay rent on centres that already exist isn't wrong, but it tells you how tight the cash cycle of a physical network can be even at an 8% adjusted EBITDA margin. It's a fair question to ask when the final prospectus lands.
Alongside the fresh issue sits an offer for sale of up to 17.86 crore shares. Inc42 lists the sellers as Temasek, Schroders Capital, LifeFit Group, Accel, Tata Digital and co-founder Mukesh Bansal. Early backers getting liquidity at listing is normal; how much each sells will be worth watching.
Two more things the filing shows
The products business is the drag
Fitness services brought in ₹1,197.83 crore in FY26 with a segment result of ₹210.08 crore. Fitness products, sold under Cultsport, brought in ₹522.77 crore with a segment result of minus ₹57.37 crore, even while growing about 60%. Growth and profitability can pull in opposite directions inside the same company, which is why segment numbers matter more than the total.
Four cities carry the business
Delhi-NCR, Mumbai, Bengaluru and Hyderabad together produced about 90% of fitness services revenue in FY26. That's both a risk and the growth pitch. A chain that has proved itself in four metros still has to show its model works where rents, prices and habits are different.
What founders can take from it
Know which profit you're talking about. Adjusted EBITDA, segment results and net profit answer different questions.
Choose your mix of owned, franchised and partner supply deliberately, and know the return on each before you scale it.
Watch the cash, not just the margin. Physical networks consume capital in fit-outs and leases long before a centre matures.
Segment honestly. A fast-growing, loss-making line can hide inside a healthy total.
If you want the method for working through the final document when it arrives, our guide on how to read a startup IPO prospectus walks through it section by section, and the per-order loss in Urban Company's new service is another case of unit economics hiding in plain sight. The price band will tell you what the market thinks Cult.fit is worth. The DRHP already tells you how hard it was to get here.