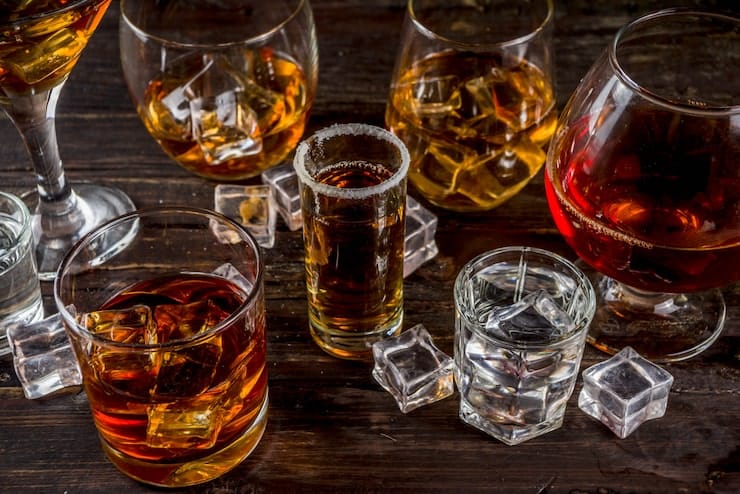
The alcoholic drinks industry across South America is evolving as changing consumer preferences, urbanization, tourism, and product innovation influence beverage consumption. Brazil, Chile, Argentina, and Colombia represent important markets with established beer, wine, and spirits industries. The region's beverage landscape includes traditional alcoholic products as well as emerging categories such as ready-to-drink (RTD) beverages, hard seltzers, and low-alcohol alternatives. These developments are encouraging manufacturers to diversify their portfolios and adapt to changing consumer expectations.
According to the market assessment published by Markntel Advisor, the South America Alcoholic Drinks Market, covering Brazil, Chile, Argentina, and Colombia, is evaluated over the 2026–2032 forecast period. The South America alcoholic drinks market research report examines industry dynamics, product segmentation, manufacturer competition, supply chains, consumption patterns, and emerging business opportunities. The study also highlights premiumization, e-commerce expansion, tourism, and sustainable production as important developments influencing the regional industry.
Beer Maintains Its Leading Position Across South America
Beer represents the leading product category in the South American alcoholic drinks industry. Its affordability, widespread availability, and established consumption culture support demand across Brazil, Argentina, Chile, and Colombia. Both multinational manufacturers and independent breweries contribute to the regional competitive landscape through mainstream, premium, and craft beverage offerings.
Brazil represents an important brewing hub, supported by established manufacturing infrastructure and extensive distribution networks. Argentina also maintains a developed beer industry, with domestic brands and independent breweries introducing differentiated products. Meanwhile, Chile and Colombia are witnessing continued product diversification through premium beers, craft varieties, and flavoured formulations.
According to Brazil's Ministry of Agriculture and Livestock, the country had more than 43,000 registered beer products in 2024. The Brazilian government's 2024 beer industry update also reported significant growth in non-alcoholic beer production. This demonstrates the diversification taking place within Brazil's established brewing industry.
Wine Production Strengthens Regional Beverage Identity
South America has an established international presence in wine production, particularly through Argentina and Chile. These countries benefit from established vineyard regions, specialized agricultural practices, and export-oriented wine industries. Brazil also contributes through its domestic wine production and expanding beverage manufacturing activities.
Argentina is internationally recognized for Malbec wines, while Chile has developed a diverse wine portfolio supported by established production regions. Wine producers are increasingly examining premium product positioning, export opportunities, and sustainable vineyard management to strengthen their competitive presence.
According to the International Organisation of Vine and Wine (OIV), Argentina produced approximately 10.9 million hectolitres of wine in 2024, while Chile recorded production of 9.3 million hectolitres. The OIV's assessment of the global wine sector highlights the importance of these countries within the Southern Hemisphere's wine production landscape.
Premiumization and RTD Beverages Encourage Product Innovation
Consumer preferences are becoming increasingly diversified across South American beverage markets. Alongside conventional beer and wine consumption, premium spirits, craft beverages, flavoured alcoholic drinks, and RTD cocktails are attracting industry attention.
Premiumization is encouraging manufacturers to introduce products differentiated through ingredients, production techniques, packaging, and flavour profiles. Spirits producers are also exploring premium formulations and regionally inspired products to strengthen their brand portfolios.
RTD beverages represent another developing category, particularly among consumers seeking convenient and pre-mixed beverage formats. Manufacturers are experimenting with fruit-based flavours, different alcohol concentrations, and packaging innovations. These developments are encouraging beverage companies to diversify beyond traditional product categories.
Tourism and E-Commerce Expand Distribution Opportunities
Tourism contributes to alcoholic beverage distribution through hotels, restaurants, bars, resorts, and entertainment establishments. Major tourism destinations across Brazil, Argentina, Chile, and Colombia provide opportunities for beverage manufacturers to reach domestic and international consumers.
Hospitality businesses also support the availability of premium spirits, regional wines, craft beers, and specialty cocktails. This creates commercial relationships between beverage producers, distributors, and food-service operators.
Meanwhile, digital commerce is transforming retail distribution. Online ordering platforms and specialized delivery services provide additional purchasing channels for consumers. In Brazil, digital beverage distribution platforms have expanded the accessibility of different beer and beverage brands. Supermarkets, liquor retailers, and specialty stores also remain important components of the regional distribution network.
Sustainability Becomes an Important Industry Consideration
Environmental sustainability is gaining attention across South America's alcoholic beverage manufacturing sector. Brewing, distilling, and winemaking require agricultural inputs, water, energy, packaging materials, and transportation resources. Manufacturers are therefore examining production methods that improve resource efficiency and reduce operational waste.
Wine producers in Argentina and Chile are exploring sustainable vineyard management, renewable energy, and more efficient water utilization. Lightweight bottles, recyclable packaging, and responsible agricultural practices are also receiving attention across the beverage supply chain.
These initiatives can support operational efficiency while helping producers respond to changing environmental expectations in domestic and international markets.
Regulatory Requirements Influence Competitive Strategies
Alcoholic beverage manufacturers across South America operate within regulatory frameworks covering taxation, licensing, advertising, packaging, and distribution. Changes in excise duties and product labelling requirements can influence manufacturing costs and commercial strategies.
Brazil, Chile, Argentina, and Colombia maintain distinct regulatory environments, requiring companies operating across multiple countries to adapt their compliance procedures. Smaller producers may face additional challenges associated with taxation, distribution costs, and regulatory administration.
Consequently, regulatory monitoring and efficient supply chain management remain important considerations for manufacturers and distributors.
Competitive Landscape and Industry Outlook
The South American alcoholic drinks industry includes established companies such as Ambev S.A., Heineken N.V., Diageo PLC, CCU S.A., Pernod Ricard, Grupo Peñaflor, and Brown-Forman Corporation. These businesses compete through product innovation, brand portfolios, manufacturing capabilities, and distribution partnerships.
Going forward, beer is expected to remain the leading product category, while wine, spirits, RTD beverages, and premium alternatives will contribute to broader market diversification. Digital distribution, sustainable manufacturing, and changing consumer preferences will continue influencing industry strategies.
Overall, the development of the South American alcoholic drinks industry will depend on manufacturers' ability to balance product innovation, operational efficiency, regulatory compliance, and changing consumer expectations across Brazil, Chile, Argentina, and Colombia.